Vitalik Buterin argues ETH as store of value makes more sense than ETH as fee-burning token
𝕏/@VitalikButerin •
Revision history
3 recorded changes
Want your article here?
Promote with Leviathan News3 recorded changes
Want your article here?
Promote with Leviathan NewsButerin argues the fee-burn "floor" was never real because burned fees came mostly from crypto-internal activity that would shrink with ETH's price. Optimizing for fees, he says, would require corporate-scale spending (~700k ETH/year, cutting validator revenue by two-thirds) and interventionist governance, plus higher gas prices. He frames ETH's value as deriving from decentralization and CROPS, with stability as the key SoV metric, and says fee burn staying under 10% of breakeven indefinitely is acceptable.
AI summary of the linked source — not editorial content.
Loading related coverage…
Loading comments…
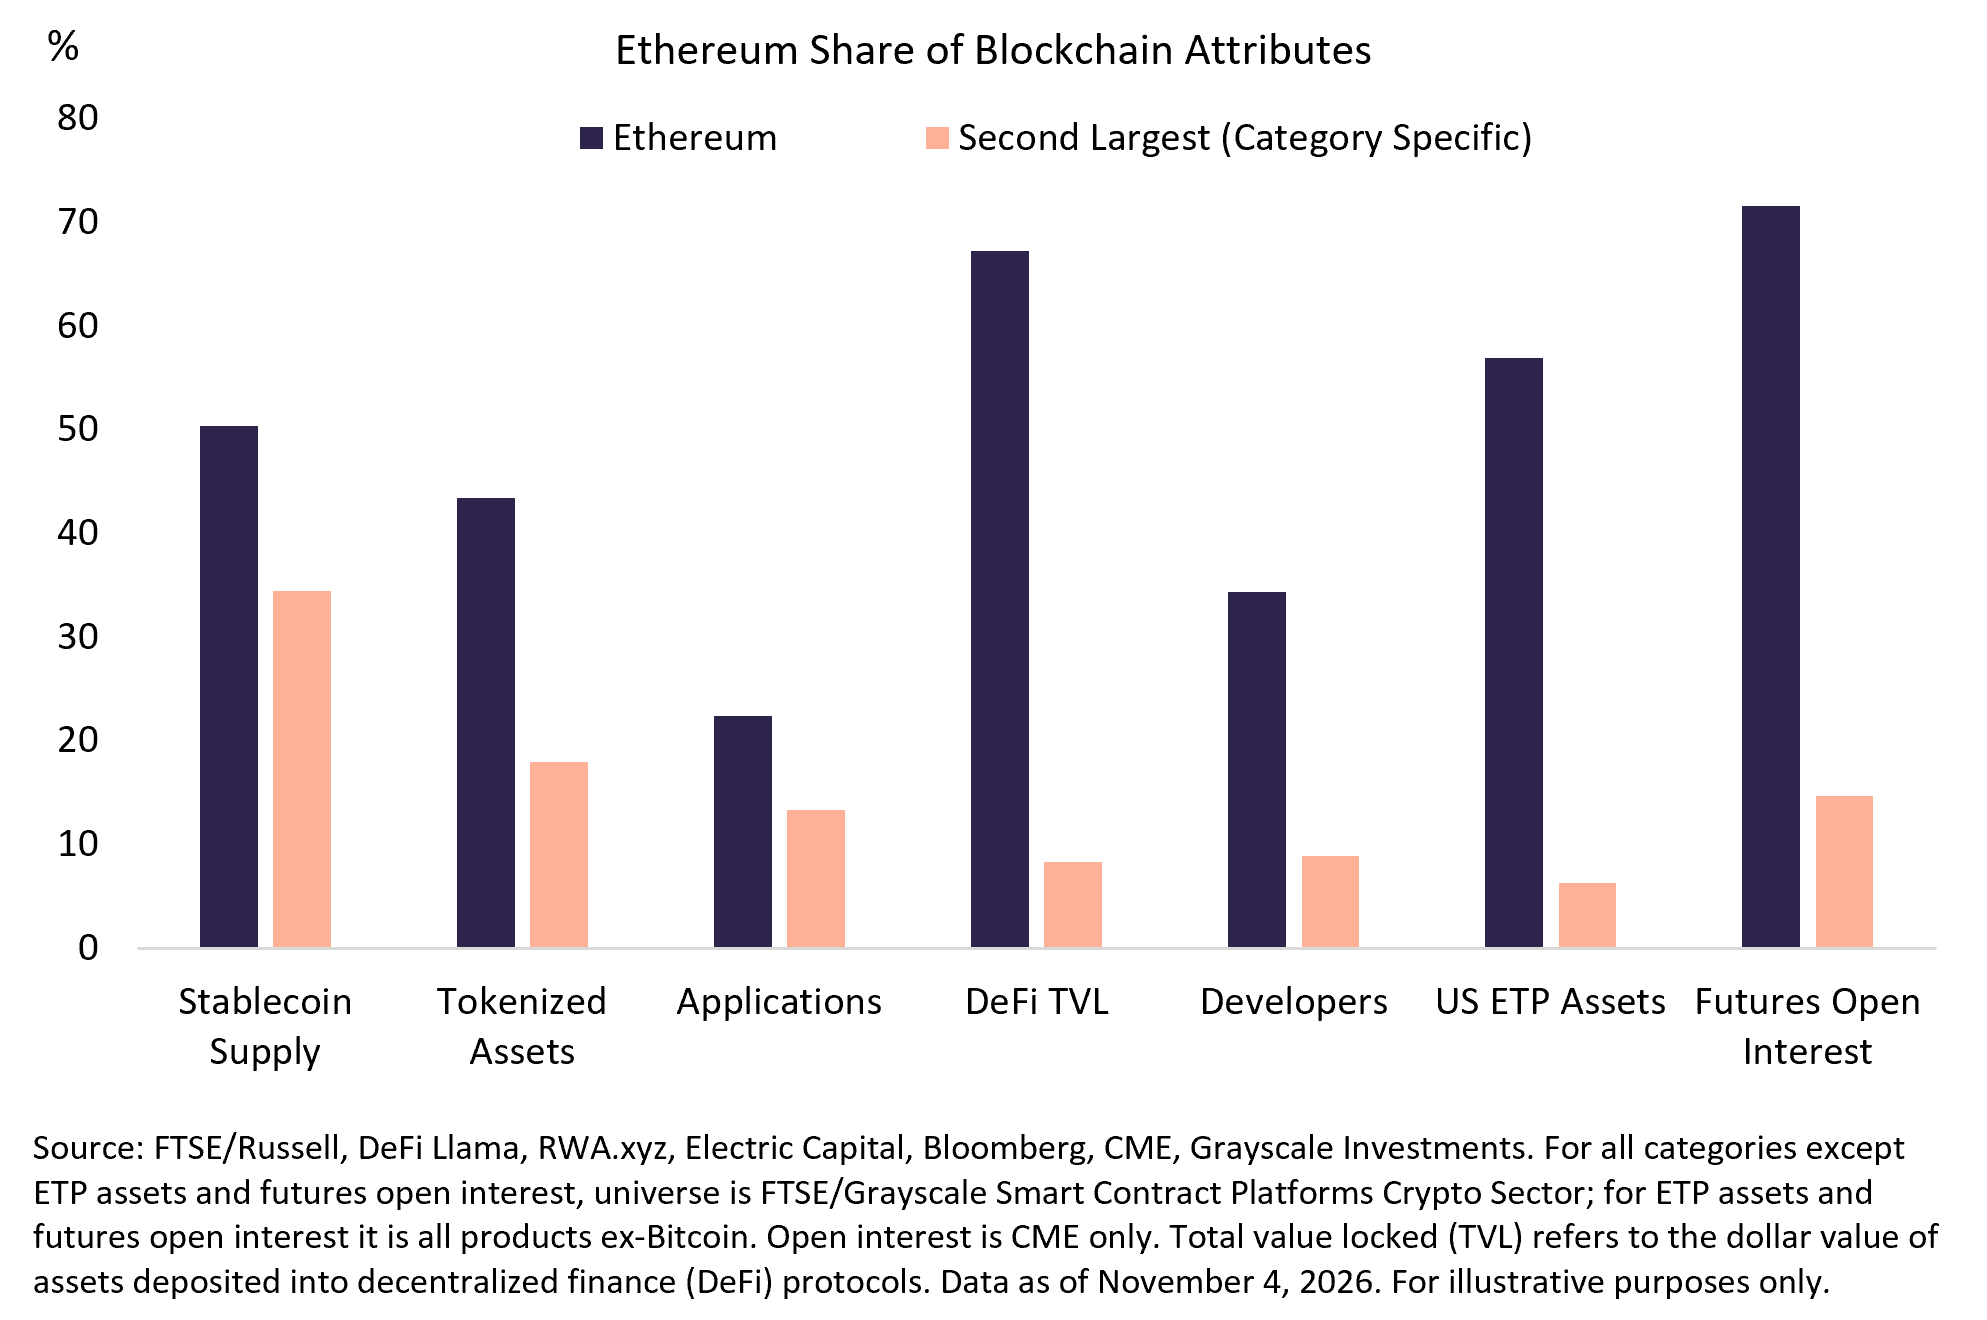
𝕏/@Grayscale ·
blog.ethereum.org ·
𝕏/@ethereuminsti ·
𝕏/@LidoFinance ·
𝕏/@zilliqa ·
𝕏/@ethereumfndn ·
𝕏/@Grayscale ·
blog.ethereum.org ·
𝕏/@ethereuminsti ·
𝕏/@LidoFinance ·
𝕏/@zilliqa ·
𝕏/@ethereumfndn ·
🚀 Love DeFi? Ready to dive in and start earning $SQUID while making an impact?
Restoring your session before loading comments…