Linus Financial settles SEC charges for unregistered crypto securities offering, avoids penalties due to cooperation and prompt remediation
sec.gov •
Revision history
2 recorded changes
Want your article here?
Promote with Leviathan News2 recorded changes
Want your article here?
Promote with Leviathan NewsThe U.S. Securities and Exchange Commission announced settled charges against Linus Financial, Inc. for offering and selling its interest-bearing crypto product, the Linus Interest Accounts, without registering them as securities under the Securities Act of 1933. Beginning around March 2020, Linus allowed U.S. investors to deposit U.S. dollars in exchange for a promise of interest; the company converted those funds into crypto assets (primarily USDC), pooled and deployed them into DeFi liquidity pools or loans to institutional borrowers, and used the returns to pay interest to investors. The SEC’s order determined that these accounts were investment contracts and therefore securities, and that Linus violated Sections 5(a) and 5(c) by not registering the offer and sale or qualifying for an exemption. Regulators highlighted Linus’s response as a model of cooperation and remediation for crypto platforms facing securities-law issues. In March 2022, shortly after the SEC brought an action against a similar crypto lending product, Linus voluntarily stopped offering new interest accounts and asked existing investors to withdraw, resulting in all customer funds being returned by late April 2022. Because the company self-closed the product, fully exited customer funds, and cooperated with the investigation, the SEC imposed no civil monetary penalties, instead issuing a cease-and-desist order barring future unregistered offerings. The case underscores the SEC’s position that many crypto yield and lending products are securities, while also signaling that proactive cooperation and prompt remediation can significantly mitigate sanctions for firms operating in the crypto asset space.
AI-generated background, compiled from web sources — not editorial content.
Loading related coverage…
Loading comments…
sec.gov ·
𝕏/@HesterPeirce ·
decrypt.co ·
crypto.news ·
𝕏/@malekanoms ·
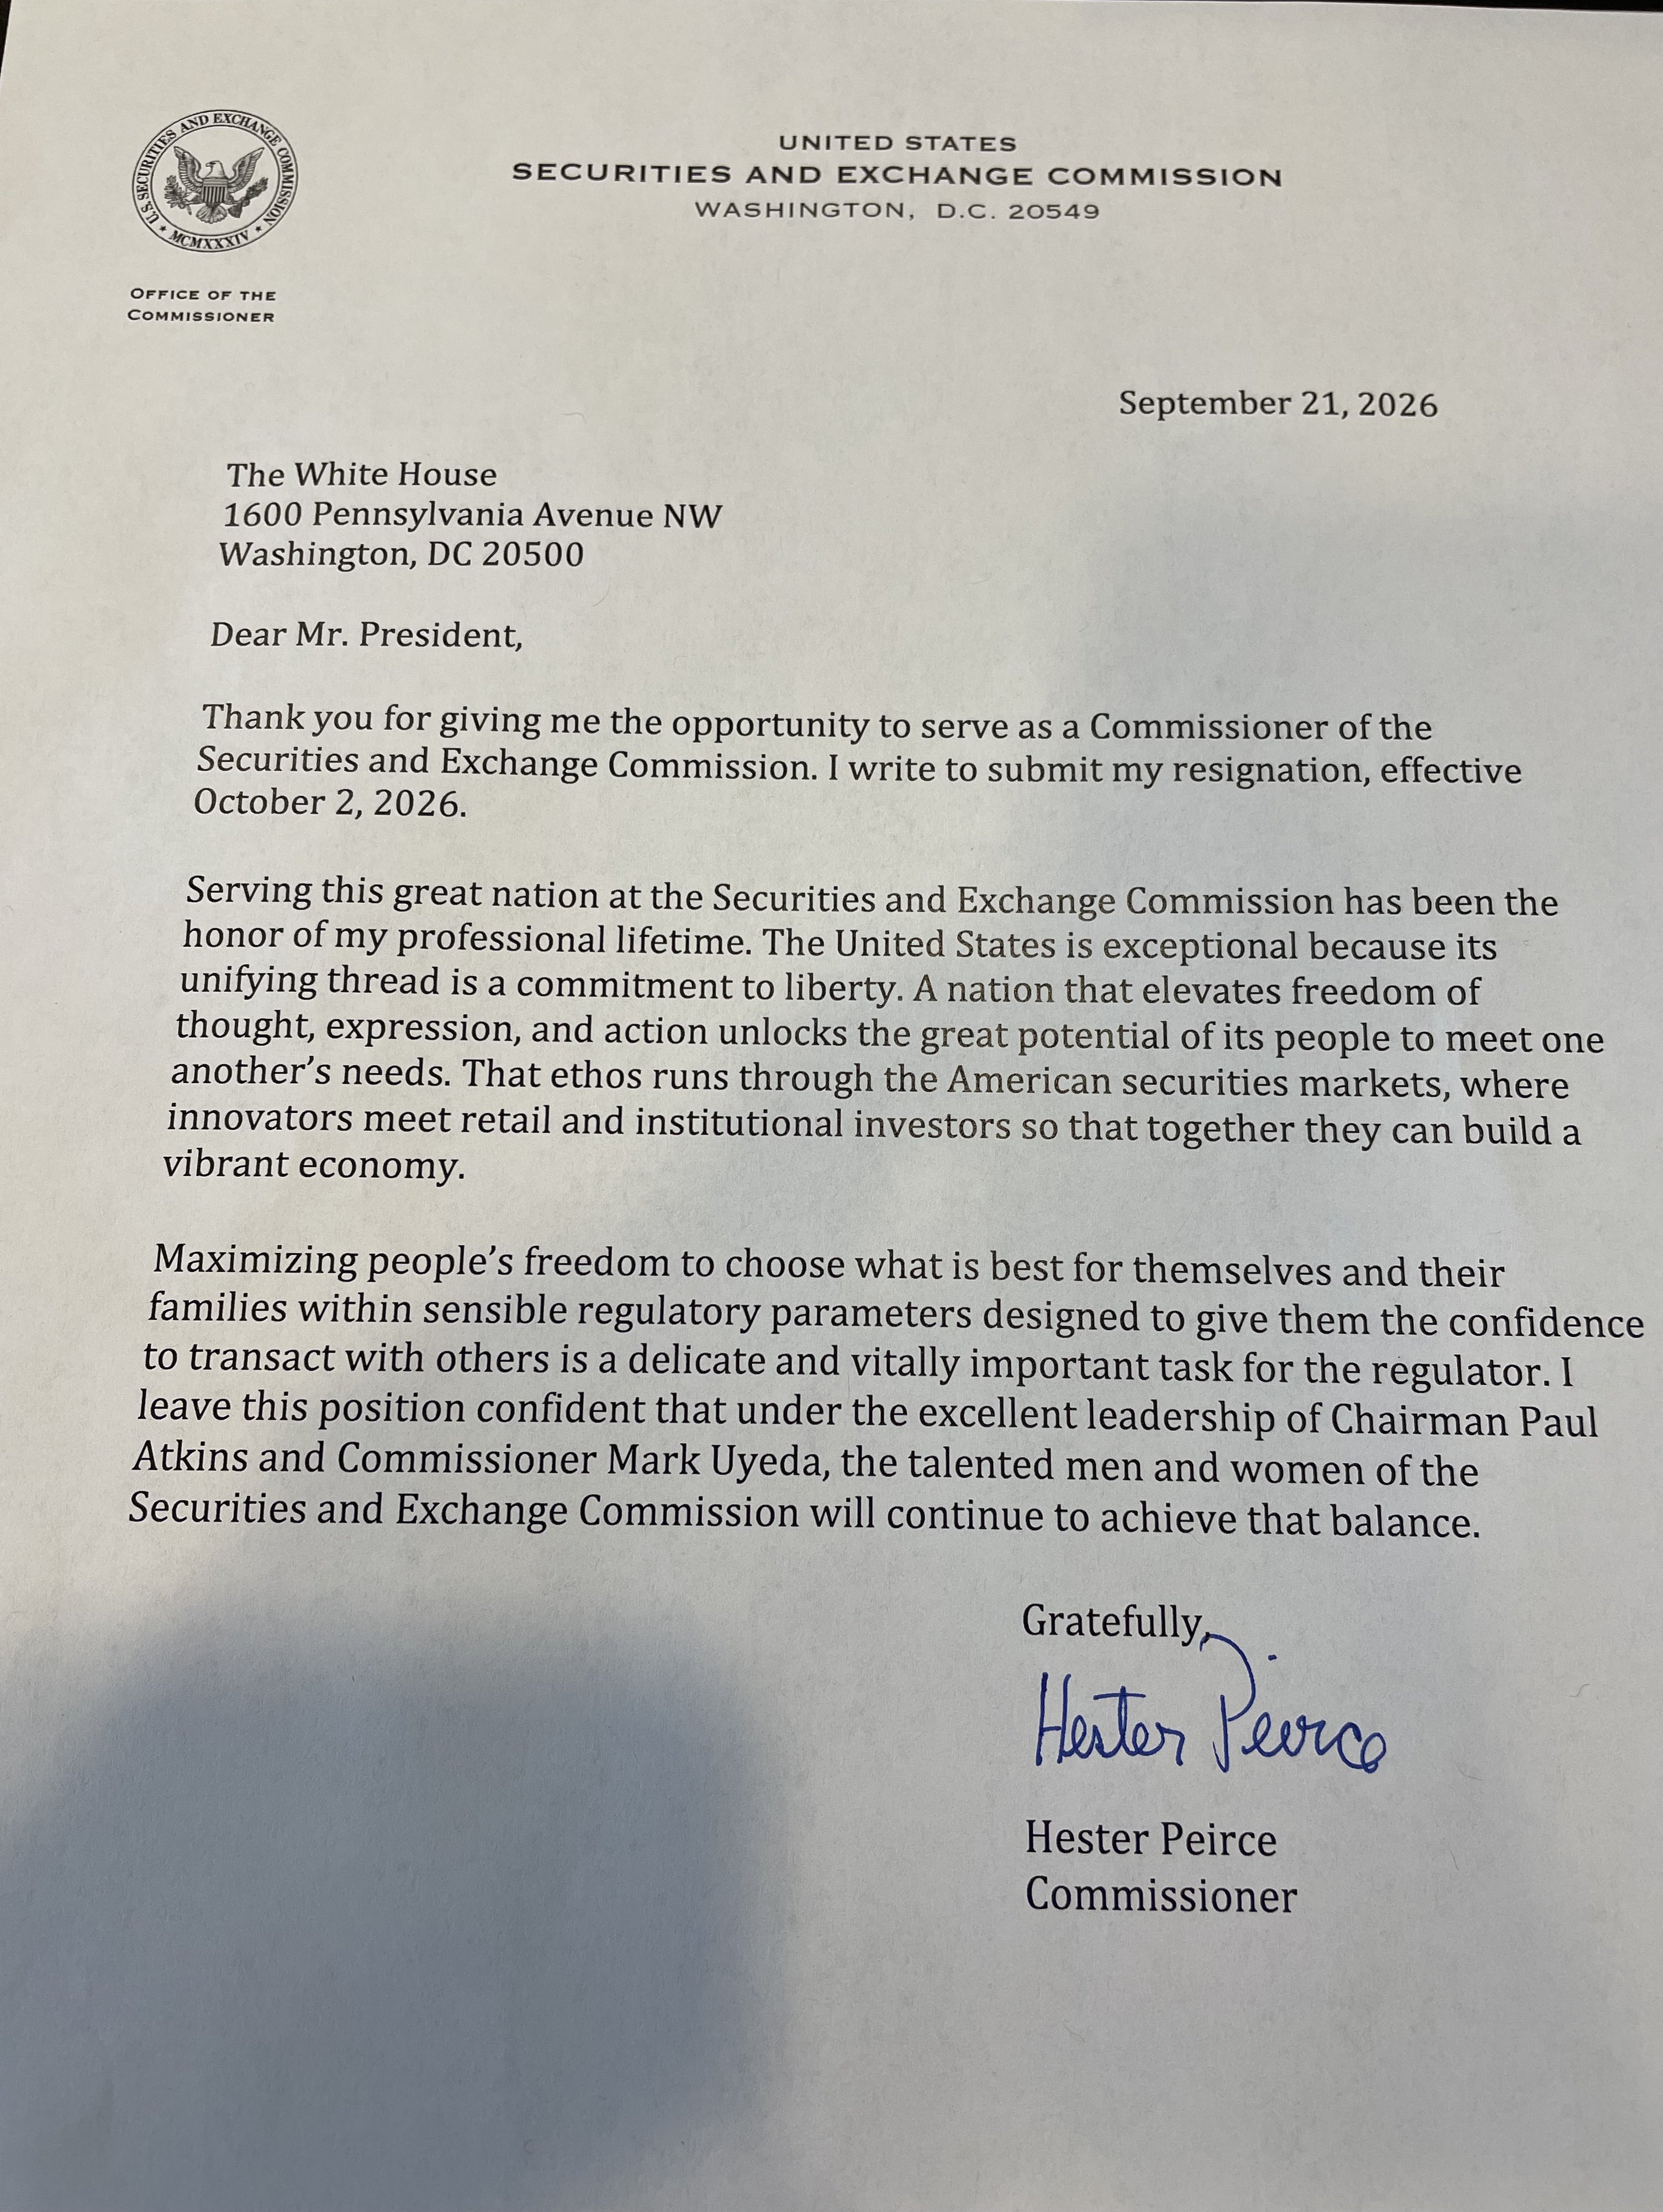
𝕏/@HesterPeirce ·
sec.gov ·
𝕏/@HesterPeirce ·
decrypt.co ·
crypto.news ·
𝕏/@malekanoms ·
𝕏/@HesterPeirce ·
🚀 Love DeFi? Ready to dive in and start earning $SQUID while making an impact?
Restoring your session before loading comments…